
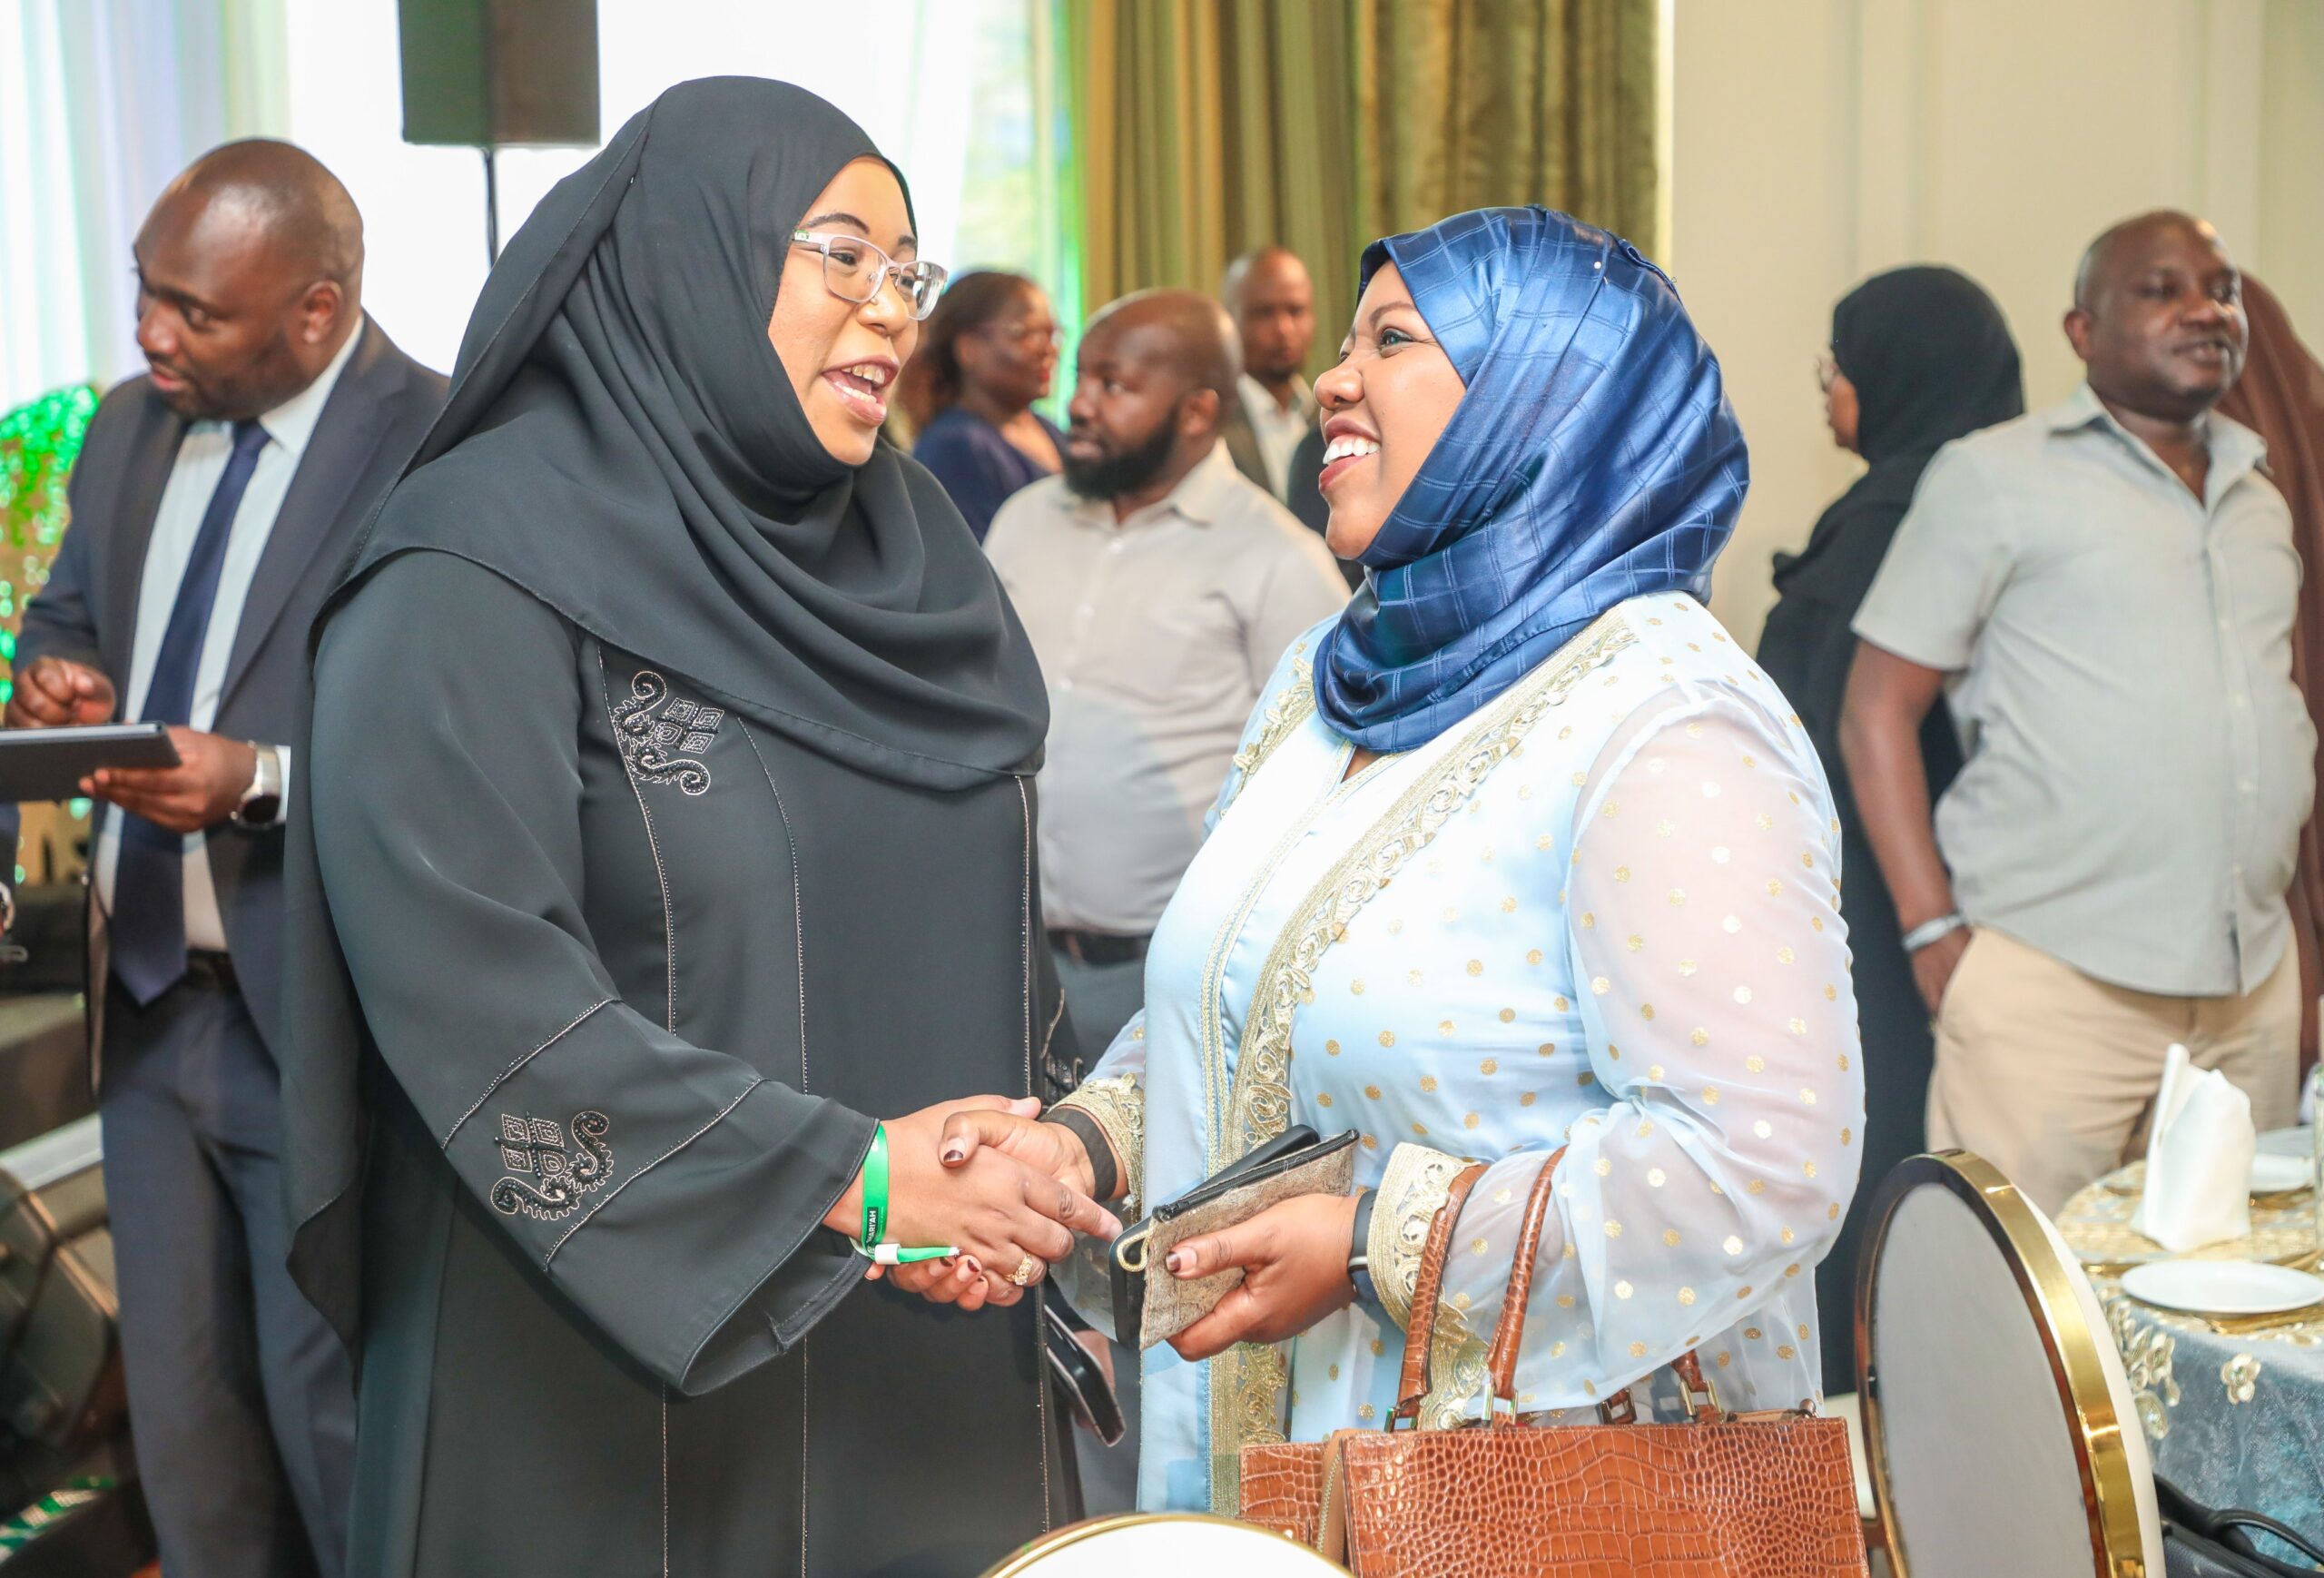
Safaricom PLC and GulfCap Investment Bank have put a money market fund inside M-Pesa that earns no interest. Ziidi Shari’ah launched on 6 October 2026, and it gives Kenyans who follow Islamic finance rules a place to save from the phone they already carry.
How Ziidi Shari’ah works
You can start with Sh100, add Sh10 at a time, and join through the My OneApp app or by dialling *334#. Deposits and withdrawals to M-Pesa cost nothing, and you can track daily profit and lock funds. The *334# menu works on any handset, so a basic phone is enough.
The fund avoids riba, the Arabic word for interest. It places money in short term, highly liquid instruments held with Shari’ah compliant banks, and returns come from permitted investment activity. GulfCap’s Shari’ah Supervisory Board oversees how the fund invests, and the Capital Markets Authority (CMA) regulates it.
You do not need to be Muslim to join. The fund is open to non Muslims, and it runs separately from Safaricom’s conventional Ziidi fund. You can hold both, manage them apart, and opt out at any time.
Who can join, and what you need
The terms and conditions set the entry rules. You must be at least 18 and have held an active M-Pesa account for three months before you apply. Safaricom can check your details against government records, and it can decline your application if you fall short. A parent or guardian can open an account for a child.
Joining makes you a unitholder. Each unit equals the e-money you invest, and the minimum purchase is Sh100 unless Safaricom announces a change. Once your account is open, you receive a statement of investment through the same channels.
Why a separate fund matters
For many Kenyans, conventional investment products were never a real choice. Faith ruled them out, so savings sat in a wallet or under a mattress.
Kenya has been slow to serve these savers. The central bank licensed its first two Shari’ah compliant banks in 2007. When the CMA approved Ziidi Shari’ah in February 2025, it counted seven firms offering Shari’ah compliant unit trusts. Meanwhile, money market funds have drawn most of the savings. As of June 2024, they held 67.4% of the Sh171.2 billion in collective investment schemes.
Safaricom’s reach explains why this launch could matter. M-Pesa has more than 41 million customers, while the conventional Ziidi fund had about 2 million at launch. Our earlier coverage traces how the platform got here: Safaricom’s entry into the money market fund business, the Ziidi MMF launch, and the CMA approval of the Shari’ah version.
What Peter Ndegwa says
Dr. Peter Ndegwa C.B.S, CEO of Safaricom PLC, argues that financial services must fit the different needs and circumstances of customers. In his words:
“When M-PESA was launched nearly two decades ago, the question was simple: how can we make it easier for people to move money?
Today, our customers are asking a different question: is this the right financial solution for me?
That shift matters.
Ziidi Shari’ah was created to give customers who want to invest in accordance with Shari’ah principles access to a simple, transparent and accessible investment option. It is another step in our journey to ensure that financial services reflect the diverse needs, values and aspirations of the communities we serve.
Whether you’re starting with KES 100 or building long-term financial security, everyone deserves access to solutions that support their goals while respecting their beliefs.”
GulfCap’s chief executive, Saud Shahbal, framed the fund as a way for Muslims, and anyone who prefers ethical investing, to grow savings in line with their values.
What the fine print says about money in and out
The terms answer the questions most savers ask first.
Timing. Money that arrives after 11am counts toward the next day’s returns. Deposit in the morning if you want the day to count.
Withdrawals. You redeem units back to your M-Pesa account through the app or USSD, and the money can take up to 72 hours to arrive. That is free, but it is not always instant. In exceptional cases, the trustee can allow a suspension of redemptions. Keep your emergency cash somewhere you can reach it the same day.
Costs. Transfers between M-Pesa and the fund carry no charge. The fund itself does pay costs. Management, custodian, trustee, marketing and administration fees come out of the fund, so they reduce the return you see each day.
Who is responsible. Safaricom supplies the technology, and the licensed fund managers carry responsibility for investing your money. Safaricom excludes liability for investment losses. KCB Bank (Kenya) Limited was named the first trustee.
Risk. The terms say the unit holder bears the full investment risk, past performance does not predict future results, and you should read the Information Memorandum before investing.
Access. Your M-Pesa PIN authorises every instruction, and you answer for what is sent on your account. Safaricom can end your registration with 30 days’ notice, and dormant accounts fall under the Unclaimed Financial Assets Act. If something goes wrong, you can send complaints through Safaricom’s contact centre channels.
What regulators are doing next
The Capital Markets Authority (CMA) wants rules that match the demand. It is drafting an overarching governance policy for Shari’ah compliant products, and its chief executive cited global Islamic finance assets of USD 3.8 trillion in 2025. He said the aim is a Shari’ah governance model that improves consistency, transparency and investor confidence.
The government is moving too. In June, Treasury Cabinet Secretary John Mbadi said the government is considering sukuk, which are Shari’ah compliant securities backed by assets. Investors in sukuk earn returns from the assets or projects behind the security, not from interest.
What to check before you invest
Shari’ah compliance describes how a fund invests. It does not guarantee a return. Five checks will help you decide:
- Read the daily rate. The rate shows on My OneApp and on *334#. Rates move, so look again after a few weeks.
- Compare net returns. In May 2026, Serrari’s tracker put the average yield across 27 Kenyan shilling money market funds at 9.11%. Judge Ziidi Shari’ah against that figure, after fees.
- Match the fund to the goal. A money market fund suits a rainy day fund or money you need within a year. Longer goals call for different products.
- Plan for the 72 hour window. Do not park money here that you may need within the hour.
- Read the paperwork. Download the full terms and conditions as a PDF and ask Safaricom for the Information Memorandum. The terms say your own independent adviser can help you decide.
The takeaway
Ziidi Shari’ah removes two barriers at once: the price of entry and the conflict with faith. Sh100 and a phone are enough to begin. The fine print asks you to accept real limits, including fees inside the fund, a withdrawal window of up to 72 hours, and full investment risk. Check the daily rate, compare it with the market, and add to the account steadily.
This article is for information only and is not financial advice.
