
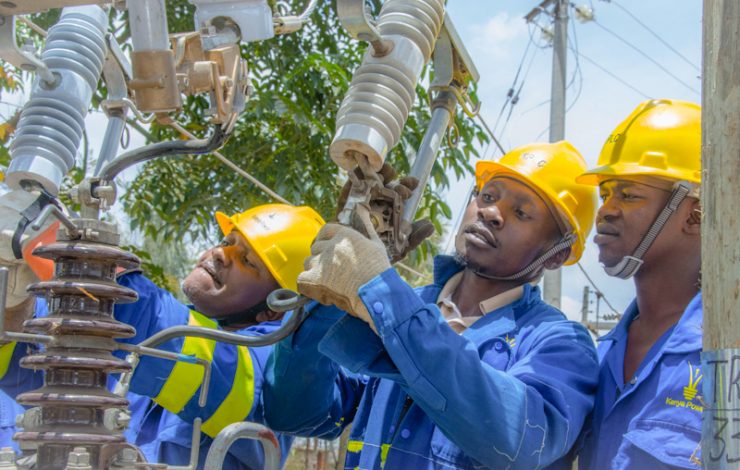
Kenya’s electricity system recorded a peak of 2,514.28 megawatts on 29 June 2026, according to the Energy and Petroleum Regulatory Authority’s statistics report for the year to June 2026. The figure exceeds last year’s record by 198 MW, a rise of 8.55 percent.
Total generation reached 15,692.81 GWh, up 8.44 percent from 14,472 GWh. Renewable sources supplied 81.13 percent of that output, against 80.48 percent a year earlier. The mix shifted within that total: geothermal rose to 40.91 percent of generation from 39.51 percent, hydro fell to 22.65 percent from 24.21 percent, and solar fell to 3.0 percent from 3.27 percent.
Households Overtake Industry in Demand Growth
Domestic consumption rose 18.87 percent to 4,327.07 GWh, compared with 13.03 percent growth a year earlier. Its share of total consumption rose from 32.13 percent to 34.77 percent. Industrial consumption grew 5.33 percent, but its share fell from 49.61 percent to 47.57 percent.
Small commercial consumption grew 5.17 percent to 2,012.17 GWh, down from 11.5 percent growth in the prior year. Street lighting rose 15.12 percent to 173.17 GWh. Electric mobility consumption rose 143 percent to 12.25 GWh, and the number of e-mobility customers rose from 115 to 543 over the year.
EPRA’s biannual report, covering the first half of FY 2025/26, recorded similar momentum across the grid. “Electricity demand increased by 8.25 per cent compared to a similar period in the previous financial year,” the report stated, tracking a rise EPRA attributed to growth in both household and industrial use.
EPRA removed the 15,000 kWh monthly cap on the e-mobility tariff from 1 July 2026. Its 2025 report had listed the change as a plan under consideration. Khusoko covered the cap’s removal on 21 September.
The Numbers, Side by Side
| Measure | FY 2024/25 | FY 2025/26 |
|---|---|---|
| Peak demand | 2,316.2 MW | 2,514.28 MW (+8.55%) |
| Electricity generated | 14,472 GWh | 15,692.81 GWh (+8.44%) |
| Renewable share of generation | 80.48% | 81.13% |
| Domestic consumption | 3,640.32 GWh | 4,327.07 GWh (+18.87%) |
| Small commercial consumption | 1,913.26 GWh | 2,012.17 GWh (+5.17%) |
| Street lighting | +43.89% | 173.17 GWh (+15.12%) |
| E-mobility consumption | 5.04 GWh | 12.25 GWh (+143%) |
| Time of Use savings | 180.3 GWh; Ksh 1.438bn | 267.6 GWh; Ksh 1.88bn |
| Electricity imports | 1,533.85 GWh | 1,913.66 GWh |
| Grid customers | 10,066,704 | 10,432,707 |
| LPG consumption | 414,861 tonnes | 475,943 tonnes (+14.72%) |
Imports From Ethiopia Rise
Imports supplied 12.19 percent of Kenya’s total energy mix, up from 10.60 percent. Ethiopia alone supplied 10.11 percent of all energy consumed in the country. Total electricity imports rose to 1,913.66 GWh, with Ethiopia’s share of imports rising to 82.45 percent and Uganda’s share rising to 16.83 percent.
EPRA’s outlook states that Kenya will increase the capacity it draws through the 500 kV HVDC link with Ethiopia from 200 MW to 400 MW in the next phase of the power purchase agreement.
Grid construction tied to that plan includes 400 kV sections between Isinya and Konza and between Isinya and Mariakani, a new Mariakani substation, and several 132 kV lines. Distribution lines across the country grew 7.23 percent to 334,157 km.
Capacity Additions Led by Menengai Geothermal
Installed capacity reached 3,987.20 MW, an increase of 146.4 MW, or 3.81 percent. The main addition came from two 35 MW geothermal plants at Menengai, built by Kaishan and Globeleq. Captive capacity outside the national grid rose 12.05 percent to 676.60 MW. Captive solar capacity rose 24.22 percent to 373.30 MW.
EPRA forecasts peak demand of 2,700 MW for the coming year, generation above 17,000 GWh, installed capacity above 4,000 MW, and a 60 MW addition at Olkaria I geothermal.
Turkana Oil Project Moves Toward First Production
The Cabinet Secretary approved the Field Development Plan for Blocks T6 and T7 on 5 November 2025. Parliament ratified the plan on 25 February 2026. Gulf Energy B.V. holds the contract, and EPRA has set 1 December 2026 as the date for first oil, a timeline consistent with separate reporting on the project’s cost review process.
Phase 1 targets output of 20,000 barrels a day. Phase 2 targets a plateau of 50,000 barrels a day. Crude will move by truck, at a rate of 100 trucks a day, to Kenya Petroleum Refineries in Mombasa. A rail link to Lokichar has been proposed for completion by 2032.
The Taifa Gas Terminal and the 30,000 tonne Asharami Synergy facility are expected to add close to 60,000 tonnes of LPG handling capacity. EPRA states that this capacity supports plans for an Open Tender System for LPG imports. LPG consumption rose 14.72 percent to 475,943 tonnes, and per capita consumption rose from 7.9 kg to 8.9 kg, a change EPRA attributes in part to the zero rating of LPG. Domestic petroleum demand rose 8.41 percent to 6.33 million cubic metres.
Oil Prices Swing Through the Year
Murban crude, the regional benchmark, moved from $69.45 a barrel in April to $110.75 in May, then to $104.44 in June. EPRA links the movement to supply disruptions in the Middle East.
Petroleum imports rose 11.52 percent to 10.88 million cubic metres over the year, with 74.8 percent sourced from the Middle East.
Leadership Changed Mid-Year
Daniel Kiptoo Bargoria, who signed EPRA’s 2025 report, resigned as Director General on 4 April 2026 following an investigation into the importation of substandard fuel. In that 2025 report, he had described the sector’s trajectory as positive, saying that “large-scale energy consumers saved about Ksh 1.438 billion through the Time-of-Use tariff” during that year.
The EPRA board appointed Dr. Eng. Joseph Oketch, then Director for Electricity and Renewable Energy, as his successor. Oketch signed the foreword to the FY 2025/26 report.
Kenya also gazetted the Energy (Electricity Market, Bulk Supply and Open Access) Regulations, 2026, which establish a wheeling framework allowing eligible consumers to buy electricity directly from generators.
Regulations on solar water heating and biofuels have been gazetted separately, and rules for e-mobility remain in development.
Figures That Do Not Reconcile
Subtracting the reported 411,710 new grid connections from the current total of 10,432,707 customers produces a figure near 10,021,000, not the 10,066,704 recorded as the base for the previous year. The gap points to differing cutoff dates between the two reports rather than a decline in connections.
The renewable energy share carries two figures in the report. The “At a Glance” page states 81.16 percent and labels it installed capacity, while the foreword states 81.13 percent for generation, a different measure. The Time of Use baseline appears elsewhere in the report as both 180.3 GWh and 180.1 GWh. The street lighting increase of 43.89 percent and the e-mobility increase of 300 percent, both cited in last year’s coverage, came from EPRA’s prior report rather than this one, so year on year comparisons throughout this story rest on EPRA’s own restated figures.
